



Free written scope consultation - allowances, timeline, and change-order rules on paper before a single trade is scheduled
Styles & brands we work with
- Kitchen remodeling
- Bathroom remodeling
- Home additions & ADU
- Roofing
- Windows & doors
- Driveway & pavers
- Fence
See the difference
 Before
 After
 Before
 After
 Before
 After
Do Impact Windows Lower Insurance in Vacaville, CA? Yes – But the Savings Work Nothing Like Florida’s
Yes, impact windows can lower your homeowners insurance in Vacaville, but not through the mechanism most articles describe. California has no state-mandated wind mitigation inspection like Florida’s OIR-B1-1802 form. Instead, Vacaville homeowners in wildland-urban interface (WUI) zones submit proof of fire-resistive construction upgrades directly to their carrier under California Insurance Code Section 2695.9, and the resulting credit typically runs 5-15% of annual premium. Call (888) 276-8078 and we’ll walk you through what your carrier will actually need.
Here’s the part that catches people: nearly every article about impact windows and insurance savings is written for Florida. Read enough of them and you’ll expect a wind mitigation inspection, a standardized form, and a discount somewhere between 10% and 45%. In Vacaville, none of that applies. The process is different, the documentation is different, and the number is smaller. Getting that straight before you spend $8,000-$25,000 on windows matters.
Why Vacaville’s Insurance Math Is a Fire Story, Not a Wind Story
Vacaville sits in a wind gap between the Coast Range and the Sacramento Valley, and that geography has shaped how carriers underwrite homes here. Delta breezes push through the gap in summer, but the bigger concern is wildfire smoke, red-flag warnings, and the WUI zones creeping into the hills and the newer edges of the city. Insurers price Vacaville homes with fire risk in mind, not hurricane wind loading. That single fact changes what a window upgrade can and can’t do for your premium.
When a standard carrier pulls back from a Solano County property, the California FAIR Plan often becomes the insurer of last resort. Recent state legislation, including AB 1816 and related FAIR Plan reforms, requires the Plan to offer premium reductions for verified fire-hardening measures – and qualifying fire-resistant glazing is on that list. If you’ve landed on the FAIR Plan, a documented window installation is one of the few levers you have to open a re-underwriting conversation.
The housing stock matters too. Vacaville’s mix runs from mid-century ranch tracts in the older core to 1990s-2000s master-planned subdivisions in Browns Valley and Nut Tree, plus newer infill on the east and north edges. Older homes often have original single-pane aluminum windows that offer no fire-resistive rating at all, which is exactly the gap a mitigation credit is designed to reward. Newer homes in the WUI zones may already have some fire-resistant construction, so the marginal credit is smaller. We look at the actual window schedule before promising any savings number.
What Actually Gets You the Credit: The Documentation Package
Your carrier’s underwriting desk isn’t looking for a receipt. It’s looking for evidence that the upgrade is real, permitted, and built to a standard. That’s where most homeowners get stuck – they install good windows, then can’t get the credit processed because the paperwork doesn’t answer the underwriter’s questions.
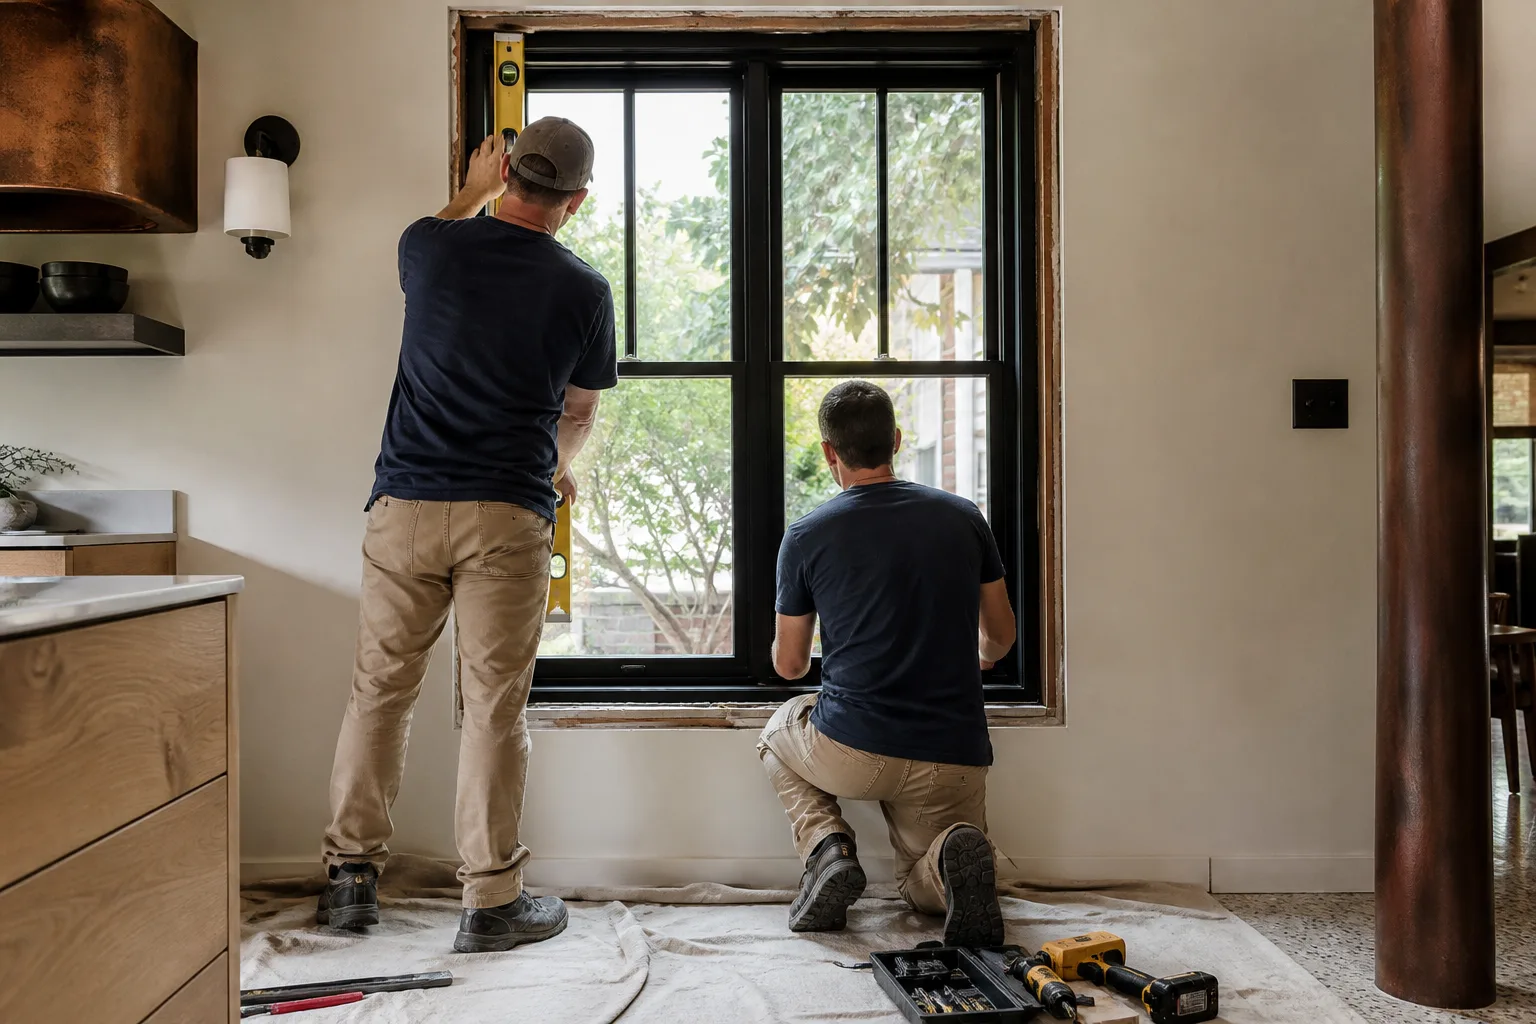
When we install Windows & Doors in a Vacaville WUI property, we build a post-installation documentation package that includes:
- Permit-closed inspection records from the city, showing the installation passed inspection under the applicable fire and energy codes.
- Product specification sheets with fire-rating certifications for each glazing unit – the manufacturer documentation your carrier’s underwriter will ask for.
- A written statement of work describing exactly what was installed, where, and to what standard.
- Reference to the active workmanship guarantee covering the installation, so the underwriter can see the upgrade is backed in writing.
That last line is where we part ways with a one-and-done installer. The 730-Day Done Right Promise – if it’s not done right, we make it right – means the installation record we hand your carrier sits behind an active guarantee. Underwriters evaluating whether a claimed fire-hardening upgrade will hold up over time tend to like that. It also means if a window fails or leaks within the coverage window, we come back, and your documented upgrade stays intact.
Do Impact Windows Lower Insurance as Much in Vacaville as in Florida?
No. The savings range is meaningfully smaller. In Florida, verified wind mitigation discounts commonly land between 10% and 45% of the wind portion of a premium. In California, verified fire-resistive glazing on a WUI property typically yields 5-15% off annual premium, and sometimes less depending on the carrier and the existing construction. A homeowner who reads a Florida article and expects a 30% cut is going to be disappointed – and might skip a window upgrade that would still pay for part of itself over a decade.
The break-even math works like this. On a $2,800 annual premium, a 10% credit is $280 a year. Spread across a $14,000 installation, that’s 50 years – so nobody should buy impact windows in Vacaville purely for the insurance discount. The credit is a real but modest tailwind. The bigger case for impact glazing here is fire-resistive construction on a WUI property, energy performance under Title 24, and the fact that a documented upgrade can keep you insurable when the standard market tightens.
What to Look For in a Vacaville Window Contractor
If you’re going to pursue the credit, the contractor matters as much as the glass. Here’s what we tell homeowners to check before signing:
- Willing to hand you a documentation package – not just a receipt. Ask upfront whether they’ll provide permit records, product spec sheets, and a written statement of work.
- Familiar with WUI and Title 24 requirements – a contractor who doesn’t know the difference between a standard replacement window and a fire-rated assembly will cost you the credit.
- Brands with documented ratings – we work with manufacturers like Andersen and Marvin for impact-rated lines, and Therma-Tru for entry systems, because the certification paperwork is what your carrier needs.
- A workmanship guarantee that outlasts the job – the 730-Day Done Right Promise is one of the longest in residential construction, and it’s the thing that makes your documentation credible to an underwriter.
Two more practical notes. Vacaville’s expansive clay soils – especially in older Browns Valley and Alamo Creek areas – cause seasonal foundation movement that shows up as sticking doors and cracked driveways every fall. Window frames and rough openings move with the house, so installation quality on a settling home is not a detail you can skip. And project timing matters: schedule exterior work for the dry months when possible, since rainy-season installs on clay-heavy lots need extra attention to drainage and flashing.
Groundwork Construction Co. of Vacaville handles the full scope – windows, doors, and the surrounding envelope work – so the documentation package reflects the whole upgrade, not just the glazing. You can see the broader service footprint on our Vacaville service area page, and the full home page covers the other trades if the project grows.
FAQs
Yes, but typically by 5-15% of annual premium, not the 10-45% wind mitigation discounts you’ll see quoted in Florida-focused articles. The credit comes through verified fire-resistive construction documentation submitted to your carrier under California Insurance Code Section 2695.9, often via the FAIR Plan’s fire-hardening provisions. Call (888) 276-8078 for a free estimate and we’ll explain what your carrier will need.
Most carriers will, provided the package includes permit-closed inspection records, product specification sheets with fire-rating certifications, and a written statement of work. We build that package for every qualifying installation and back it with the 730-Day Done Right Promise. Call (888) 276-8078 to talk through your specific carrier’s requirements – estimates are free.
Impact window installation in Vacaville typically runs $8,000-$25,000 depending on the number of openings and the rating required. Standard window replacement falls in the $4,500-$15,000 range. Neither price includes the insurance credit, which is applied separately after installation and documentation. Call (888) 276-8078 for an upfront, no-surprises quote on your specific window count.
Possibly. Recent FAIR Plan reforms require the Plan to recognize verified fire-hardening measures including fire-resistant glazing, which means a documented installation can open a re-underwriting conversation. We can’t promise a specific credit – that’s between you and your carrier – but we can make sure the documentation you submit is complete. Call (888) 276-8078 for a no-pressure assessment.
Often yes, because the insurance credit is only one of the benefits. Fire-resistive glazing on a WUI property, better energy performance under Title 24, and documentation that keeps your home insurable when the standard market tightens all add up. Treat the premium credit as a tailwind, not the whole case. Call (888) 276-8078 to talk through whether it makes sense for your property.
Talk to Someone Who Knows the Difference
If you’d rather have this looked at by people who know the California process, Groundwork Construction Co. of Vacaville offers a no-pressure assessment in Vacaville – call (888) 276-8078. We’ll tell you straight what credit is realistic for your property, what documentation your carrier will need, and what the installation will cost with upfront pricing. Calls are answered by a live person, 24/7, and free estimates come with no obligation. Financing at 0% for 18 months and $1,000 off projects over $10,000 are available if you decide to move forward.
Written by the team at Groundwork Construction Co. of Vacaville, serving Vacaville, CA.


